This checklist provides a practical method to evaluate molder financial stability. It covers audit points for supplier risk, capacity, and long-term supply continuity, helping buyers make informed sourcing decisions.
- Verify molder financial stability by reviewing audited financial statements and credit reports before signing long-term contracts.
- Assess molder capacity through documented machine utilization rates, tooling footprint, and production schedules.
- Screen for supplier risk by checking insurance coverage, single-source dependencies, and contingency planning.
- Prioritize molders with transparent communication and documented capacity expansion plans for future growth.
- Revisit financial and capacity reviews annually to detect early warning signs before supply disruptions occur.
Why Financial Stability Matters in Molder Selection
A molder financial stability check protects your production schedule and part supply. When a supplier cannot meet payroll, service tooling, or maintain machine uptime, your line stops. The risk grows when a molder operates at high utilization, lacks backup capacity, or relies on a single customer for revenue.
This checklist walks through the key areas to audit: financial health, production capacity, risk exposure, and operational continuity. The goal is not to pick the largest or cheapest molder, but to confirm they can deliver your parts through demand fluctuations, material price changes, and unexpected disruptions.
Section 1: Financial Health and Liquidity
Start with the numbers. A molder with strong cash flow, low use, and diversified revenue is more likely to invest in new tooling, maintain machines, and honor long-term agreements.
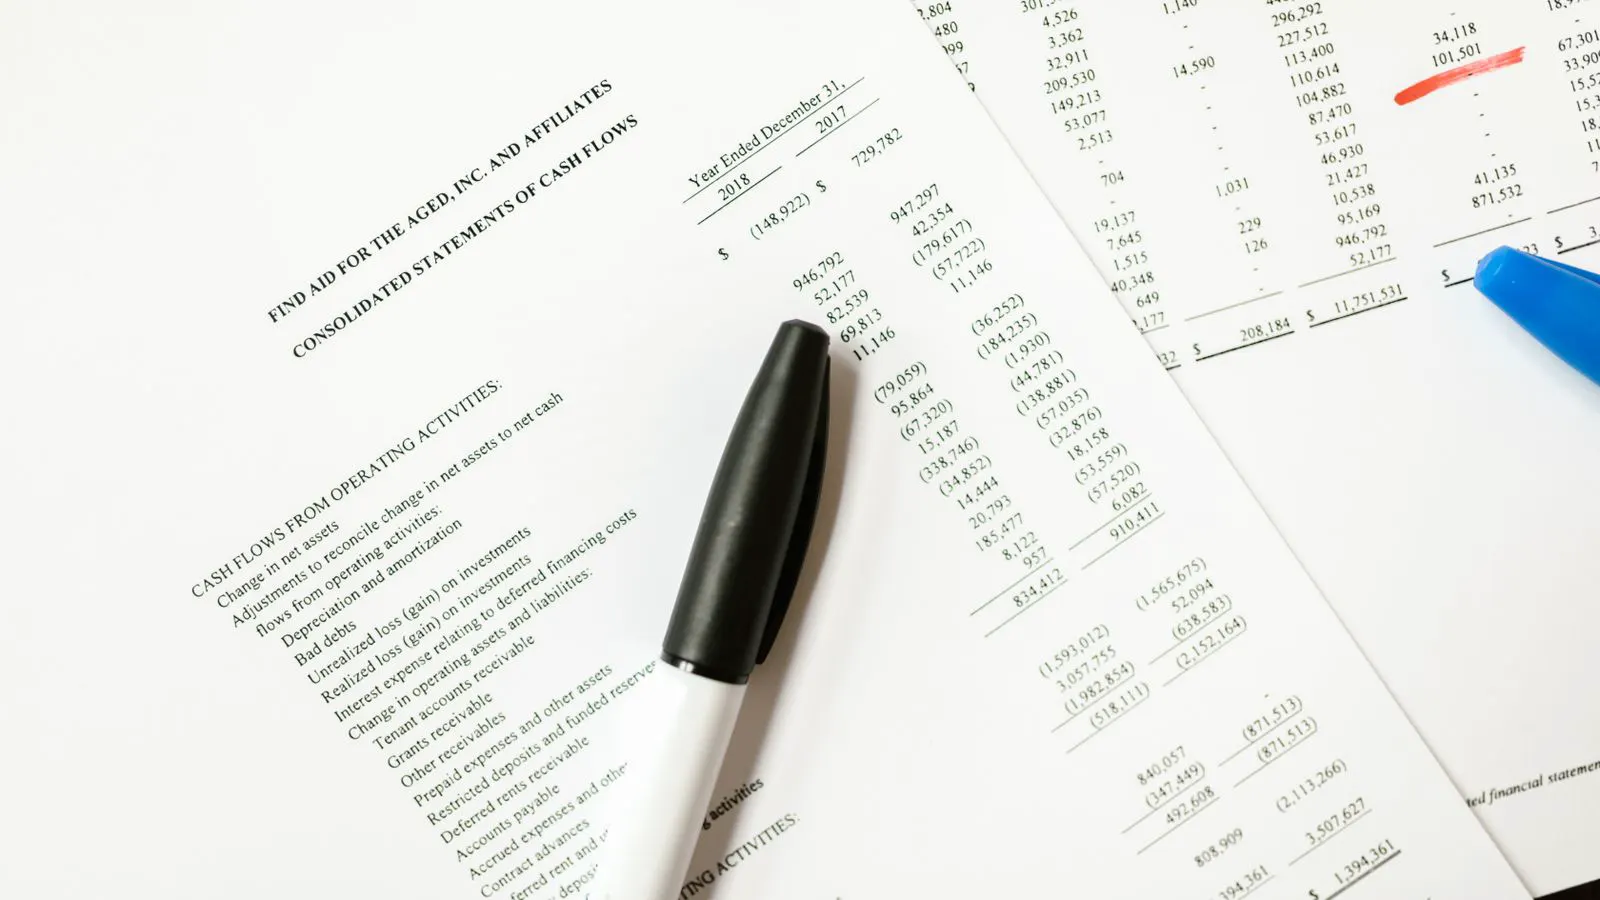
- Request audited financial statements for the last two years. Look at revenue trends, gross margin, and net income. A steady or growing margin suggests the molder is profitable enough to fund capital projects.
- Ask for a current credit report from a commercial credit agency. Pay attention to the credit score, payment terms offered, and any overdue balances from other suppliers.
- Check debt-to-equity ratio. A high ratio means the molder is carrying significant borrowing. If rates rise or revenue dips, debt service can crowd out maintenance and staffing.
- Review customer concentration. If one or two clients make up a large share of revenue, a single contract loss can trigger layoffs, tooling delays, and reduced capacity.
- Ask about reserve funds. Molders with cash reserves can weather short-term revenue dips without cutting maintenance or service hours.
Red flags: declining margins for two consecutive years, a sudden drop in revenue, high reliance on one customer, or refusal to share financial data. A molder that will not provide basic financial information is signaling weakness or risk.
Section 2: Capacity and Machine Footprint
Molder capacity determines whether your parts can ship when you need them. Even a financially stable molder can fail if they are at full utilization and cannot absorb demand spikes or tooling delays.
- Ask for a machine list by injection molding press. Record tonnage, number of cavities, and current utilization percentage. A press at 90 percent or higher utilization leaves little room for new tooling, changeovers, or quality holds.
- Request a capacity utilization report. This should show how much of the scheduled time is already committed to existing customers. If most of the capacity is locked in, your new parts will compete for limited slots.
- Check tooling footprint. How many active tooling sets are on the floor? A high number of active tools means changeover time is longer and the floor is less flexible.
- Ask about dedicated versus shared capacity. Dedicated capacity reduces changeover time and improves quality consistency. Shared capacity is more cost-effective but adds scheduling risk.
- Request a 12-month production schedule. Review whether your parts fit into the existing plan without displacing other customers.
Red flags: utilization above 85 percent, a growing backlog, no dedicated capacity for your parts, or a schedule that shifts frequently. These signs suggest the molder is stretched thin and may delay your tooling or production.
Section 3: Supplier Risk and Contingency Planning
Supplier risk goes beyond money. It covers the likelihood that a molder will fail to deliver due to equipment breakdown, labor shortage, material shortage, or external disruption.
- Ask for a written contingency plan. A good plan identifies single points of failure and defines backup actions. For example, if a critical press fails, which backup press will run the tooling, and how quickly?
- Review insurance coverage. Confirm general liability, property, and business interruption coverage. Business interruption coverage can help a molder continue operations after a fire, flood, or major equipment failure.
- Check single-source dependencies. If a molder relies on one supplier for a critical material, machine part, or service, a disruption at that supplier can halt production.
- Ask about labor planning. How does the molder handle shift coverage, key operator turnover, and seasonal demand? A shortage of experienced operators can cause quality issues and schedule delays.
- Review the molder’s response to past disruptions. Ask for examples of how they handled a machine failure, material shortage, or customer cancellation. Their answer reveals whether they have a real plan or just a policy document.
Red flags: no written contingency plan, no backup press identified, no insurance confirmation, or a history of unresolved customer complaints related to delivery. These signs suggest the molder is not prepared for operational risk.
Section 4: Operational Continuity and Service Capability
Long-term supply depends on more than production. It depends on the molder’s ability to maintain machines, service tooling, and respond to quality issues.
- Ask for a preventive maintenance schedule. This should cover injection molding machines, molds, and ancillary equipment. A documented schedule reduces unplanned downtime.
- Review tooling service capability. Does the molder have in-house tool repair, or do they outsource? In-house service speeds up fixes and keeps your tooling on-site.
- Check quality management systems. ISO 9001, ISO 13485, or similar standards provide a baseline for process control. For medical or automotive parts, verify the specific standard and scope of certification.
- Ask about change management. How does the molder handle design changes, material substitutions, and process adjustments? A clear process prevents unauthorized changes that cause rework.
- Request a service level agreement. Define response times for quality issues, tooling service, and schedule changes. A written agreement sets expectations and provides a basis for corrective action.
Red flags: no preventive maintenance record, no defined service level, or a history of unexplained quality escapes. These signs suggest the molder does not have the discipline to maintain long-term supply.
Section 5: Communication, Responsiveness, and Relationship Management
A molder financial stability review is incomplete without assessing how the molder communicates. A financially sound molder that does not respond to emails, misses meetings, or provides vague answers is a risk.
- Test responsiveness. Send a sample question and measure response time. A molder that takes days to reply to a basic inquiry may take longer to resolve a production issue.
- Ask for a dedicated account manager. A single point of contact reduces confusion and speeds up decision-making.
- Request a quarterly business review schedule. These meetings should cover production performance, quality metrics, capacity plans, and risk updates.
- Check the molder’s escalation process. Who do you call when a problem occurs? Is there a defined path from line level to management?
- Review the contract. Look for clear terms on capacity, pricing, change orders, and termination. Ambiguity in the contract creates friction later.
Red flags: slow responses, no dedicated contact, no quarterly review, or a contract that lacks clear capacity and pricing terms. These signs suggest the molder is not built for a long-term partnership.
Section 6: Capacity Expansion and Growth Planning
If your part demand will grow, the molder must be able to scale. A molder that cannot expand capacity will eventually become a bottleneck.
- Ask about planned capacity investments. Are they adding machines, tooling, or shifts? A growth plan shows the molder is investing in the future.
- Check the molder’s capital budget. A molder with a funded capital budget can add equipment without taking on risky debt.
- Review the molder’s expansion timeline. If they plan to add capacity in 12 to 24 months, align your growth forecast with their plan.
- Ask about labor availability. Can they hire the operators and engineers needed to run new capacity? Labor shortages can delay expansion.
- Request a capacity forecast for the next three years. This should show planned equipment, tooling, and shift changes.
Red flags: no capital plan, no growth forecast, or a molder that cannot say when new capacity will be available. These signs suggest the molder cannot support your long-term needs.
How to Use This Checklist
Print this checklist and use it during your molder audit. Assign each section to a specific stakeholder: finance for Section 1, production for Section 2, supply chain for Section 3, quality for Section 4, and procurement for Section 5 and 6.
| Section | Key Documents | Owner |
|---|---|---|
| Financial Health | Audited statements, credit report | Finance |
| Capacity | Machine list, utilization report | Production |
| Supplier Risk | Contingency plan, insurance certificates | Supply Chain |
| Operational Continuity | Maintenance schedule, service level agreement | Quality |
| Communication | Response logs, account manager contact | Procurement |
| Capacity Expansion | Capital budget, three-year forecast | Procurement |
Complete the checklist before you sign a long-term agreement. Revisit it every 12 months, or after any major change in your part demand, material, or volume. A molder financial stability check is not a one-time task. It is an ongoing process that keeps your supply chain aligned with your business.
Common Mistakes to Avoid
- Relying on a single molder without a backup. Even a strong molder can face disruption.
- Ignoring utilization rates. A molder at 95 percent utilization will delay your parts when they need them.
- Skipping the contingency plan review. A plan on paper is only useful if the molder can execute it.
- Not testing responsiveness. A slow response during the audit is a preview of how they will respond during a production issue.
- Assuming a good quote means good long-term value. A low price today can become a high cost tomorrow if the molder cannot maintain quality or capacity.
Final Note
The goal of this checklist is simple. Confirm that the molder can pay its bills, run the machines, service the tooling, and communicate clearly. When you can answer yes to each of those questions, you have a solid foundation for a long-term supply relationship. If you cannot, do not sign the contract. Keep looking.
Frequently asked questions
How often should I review a molder financial stability check?
Review it at least annually, or after any major change in part demand, material, or volume. If the molder experiences a financial or operational disruption, review it immediately.
What is the best way to verify molder capacity?
Request a machine list, utilization report, and 12-month production schedule. Cross-check the numbers with your own part requirements to confirm there is room for your production.
How do I know if a molder has a real contingency plan?
Ask for a written plan and specific examples of how it was used during past disruptions. A plan without examples is likely a policy document, not an operational tool.
What is the risk of a molder with high customer concentration?
High customer concentration means one or two clients make up a large share of revenue. If one of those clients leaves or reduces volume, the molder may face cash flow pressure, tooling delays, or reduced capacity.
Should I require a molder to share financial statements?
Yes, for long-term or high-volume contracts. Request audited statements or a credit report. If a molder refuses to share basic financial information, treat it as a red flag and look for another supplier.